For LNG shipping, the question of vessel size has always involved a careful trade-off. Increasing cargo capacity can improve transport efficiency, but those gains have limited value if a ship becomes too large for the infrastructure it needs to serve.
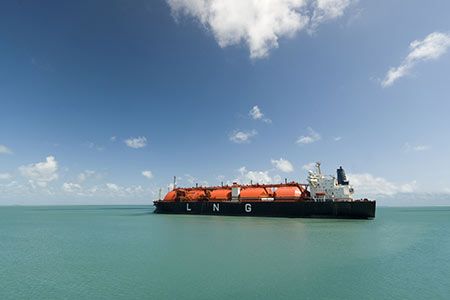
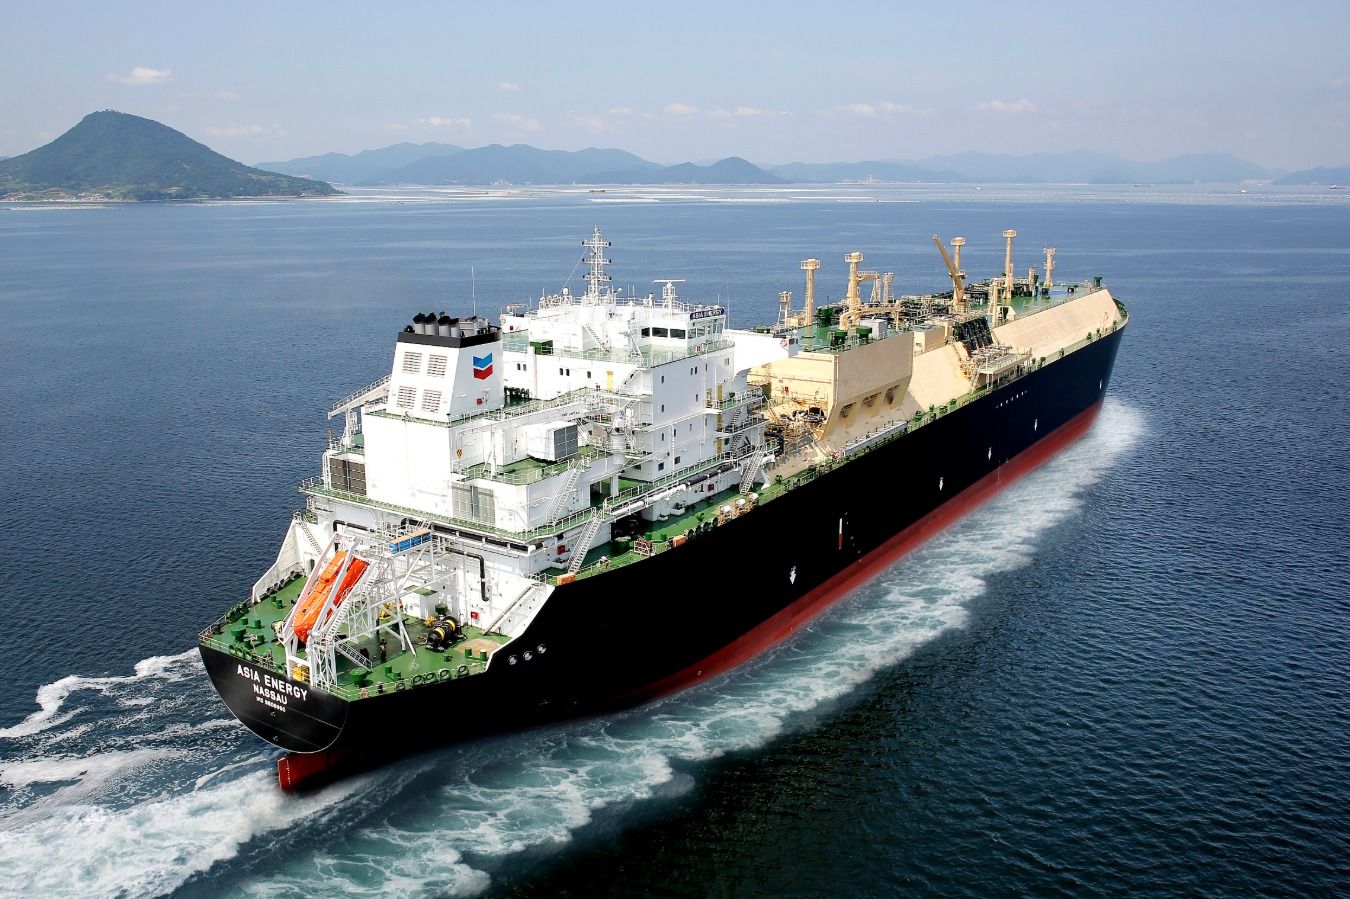
A new technical and commercial assessment of 200 000 m3 LNG carrier concepts, produced by LR Advisory for GTT and presented at Gastech 2026, suggests the industry may be approaching a useful middle ground, where vessels are significantly larger than the conventional 174 000 m3 LNG carrier, but still capa-ble of accessing much of the existing global terminal network.
LR analysis compared representative 200 000 m3 designs with a 174 000 m3 LNG carrier, examining terminal accessibility alongside representative commercial Atlantic and Pacific operating scenarios.
It found that a 200 000 m3 vessel could access approximately 88 LNG termi-nals globally, compared with 97 for its 174 000 m3 counterpart.
The reduction in accessibility is important, but the geographical distribution of those restrictions matters. Modern terminals in China, South Korea, Singapore, and Northern Europe are generally compatible with 200 000 m3 LNG carrier operations. Restrictions are more concentrated among older terminals, particularly in Japan.
This distinction could prove central to the case for upsizing. Rather than re-quiring a fundamental rebuilding of the LNG terminal network, a 200 000 m3 vessel could potentially operate across many of the trades already central to the global LNG market.
“The significance of these findings is that larger LNG carriers do not appear to require a wholesale rethink of terminal infrastructure,” said Constantinos Chaelis, Global Gas Segment Director at LR. “Many key LNG hubs are already capable of supporting these vessel concepts, which gives the market a realistic pathway to improve transport efficiency while maintaining broad trading optionality.”
This assessment considered eight representative 200 000 m3 three and four-tank vessel concepts. Overall lengths of these notional ships ranged from 291.4 m to 300 m and beam from 47 m to 51 m, with a draught of 11.5 m.
Interestingly, cargo tank configuration itself did not emerge as the determining factor in terminal accessibility. Based on the vessel particulars and terminal constraints reviewed, the analysis identified no material difference in terminal accessibility between three and four-tank arrangements. The more significant factor was beam.
Beam restrictions were the most common limitation, followed by displacement. Draft restrictions were relatively limited, while vessel length proved generally less critical than anticipated. One 51 m-beam concept encountered restrictions at terminals with a 50 m beam limit, showing how small adjustment to dimensions can materially affect trading flexibility.
This creates an important distinction for future design development. Displacement compatibility can sometimes be influenced by the loading condition and cargo density, and therefore assessed during voyage planning and terminal acceptance. A beam restriction is inherently harder to mitigate against without changing the vessel design.
“The conclusion is not simply that bigger LNG carriers work, but that careful optimisation of their principal dimensions matters. Capacity needs to be increased without moving the vessel beyond the infrastructure envelope required by its intended trading pattern,” added Chaelis.
The potential case for larger LNG carriers also needs to be viewed against changing operating patterns.
The report identifies increasing LNG trade volumes, longer-haul trades, an ageing fleet, and a greater focus on efficiency and reducing emissions among the structural factors influencing the market. It also points towards the use of lower operating speeds as the industry seeks greater efficiency.
The assessment refers to operating speeds of around 15.3 knots compared with traditional LNG carrier speeds of about 19 knots. As lower speeds reduce the number of voyages that can be completed over a given period, additional transportation capacity may be needed to compensate.
A larger vessel means more LNG can be transported on each voyage, potentially reducing the number of sailings required per unit of cargo moved and improving overall transport efficiency.
“The industry is entering a period where fleet renewal decisions will shape LNG transportation for decades to come,” commented Sujith Tooneri, one of the authors of the detailed feasibility assessment.
“Our analysis shows that 200 000 m3 LNG carriers can retain access to most major LNG terminals while increasing cargo carrying capacity, making them a practical option for owners looking to improve transportation efficiency and support future trade growth.”
The issue is relevant to fleet renewal as the assessment notes an ageing LNG carrier fleet requiring replacement alongside growing LNG trade volumes, strong shipyard orderbooks, and demand for more efficient vessel designs.
Greater capacity must still justify the additional investment. Here, the model-ling provides a further argument for considering the 200 000 m3 scale.
Under the representative scenarios modelled in the study, the assessment indicates approximately US$85 million in additional owner benefit over 30 years, with a net present value of US$78.1 million, an internal rate of return of 8.3% and an estimated payback period of approximately 10 years.
The potential benefits for charterers are larger in absolute terms under the assumptions modelled. The study estimates a 30-year benefit of US$1.38 billion for a US-Europe trading scenario under EU regulations and US$1.48 billion for the same trade under the modelled IMO framework.
For the longer US-Asia trade, the equivalent modelled benefits are US$680.4 million under the IMO framework and US$804.2 million in the scenario without regulations.
These figures should not be read as forecasts of financial performance. The report states that the benefits are based on representative trading scenarios, market assumptions, and modelling conducted as part of the study.
Actual performance may vary depending on market conditions, vessel design, and operational profile.
And that caveat is important. So too is the relatively modest difference in the headline terminal-access figures. The commercial assessment moves from 97 accessible terminals for a conventional 174 000 m3 carrier to 88 for the larger ves-sel, while increasing nominal cargo capacity by 26 000 m3.
The case for the 200 000 m3 LNG carrier is therefore more nuanced than simply building a larger ship.
For the next generation of LNG carriers, the debate may be less about whether the fleet should become larger and more about how far it can scale while retaining sufficient flexibility.
“The 200 000 m3 concept does not remove every infrastructure constraint, nor will it suit every trade. What the analysis shows is that the step from 174 000 m3 to 200 000 m3 can be technically feasible across much of the existing terminal network and commercially attractive under the scenarios assessed,” stated Tooneri.
For an industry preparing to make fleet decisions with implications stretching decades into the future, that changes the discussion.
“The question is no longer simply whether LNG carriers can become larger, but whether additional capacity can be designed into the next generation of vessels while preserving the flexibility that has made the modern LNG fleet globally tradable,” concluded Chaelis.